
Welcome:
Login
|
Sign Up
|
About CircleID
Follow:
|
|

|
||
|
||
Based on IPv4.Global’s October 2026 market report, this analysis examines recent pricing trends, transaction activity, and evolving market dynamics shaping the outlook for IPv4 addresses.
The IPv4 market strengthened further in October, with average prices rising across all major allocation categories while transaction volumes remained steady. The latest results extend a recovery that began during the spring, reinforcing evidence of sustained operational demand amid increasingly constrained availability. Although appreciation remains measured, the changing relationship between block sizes is becoming an important feature of the market.
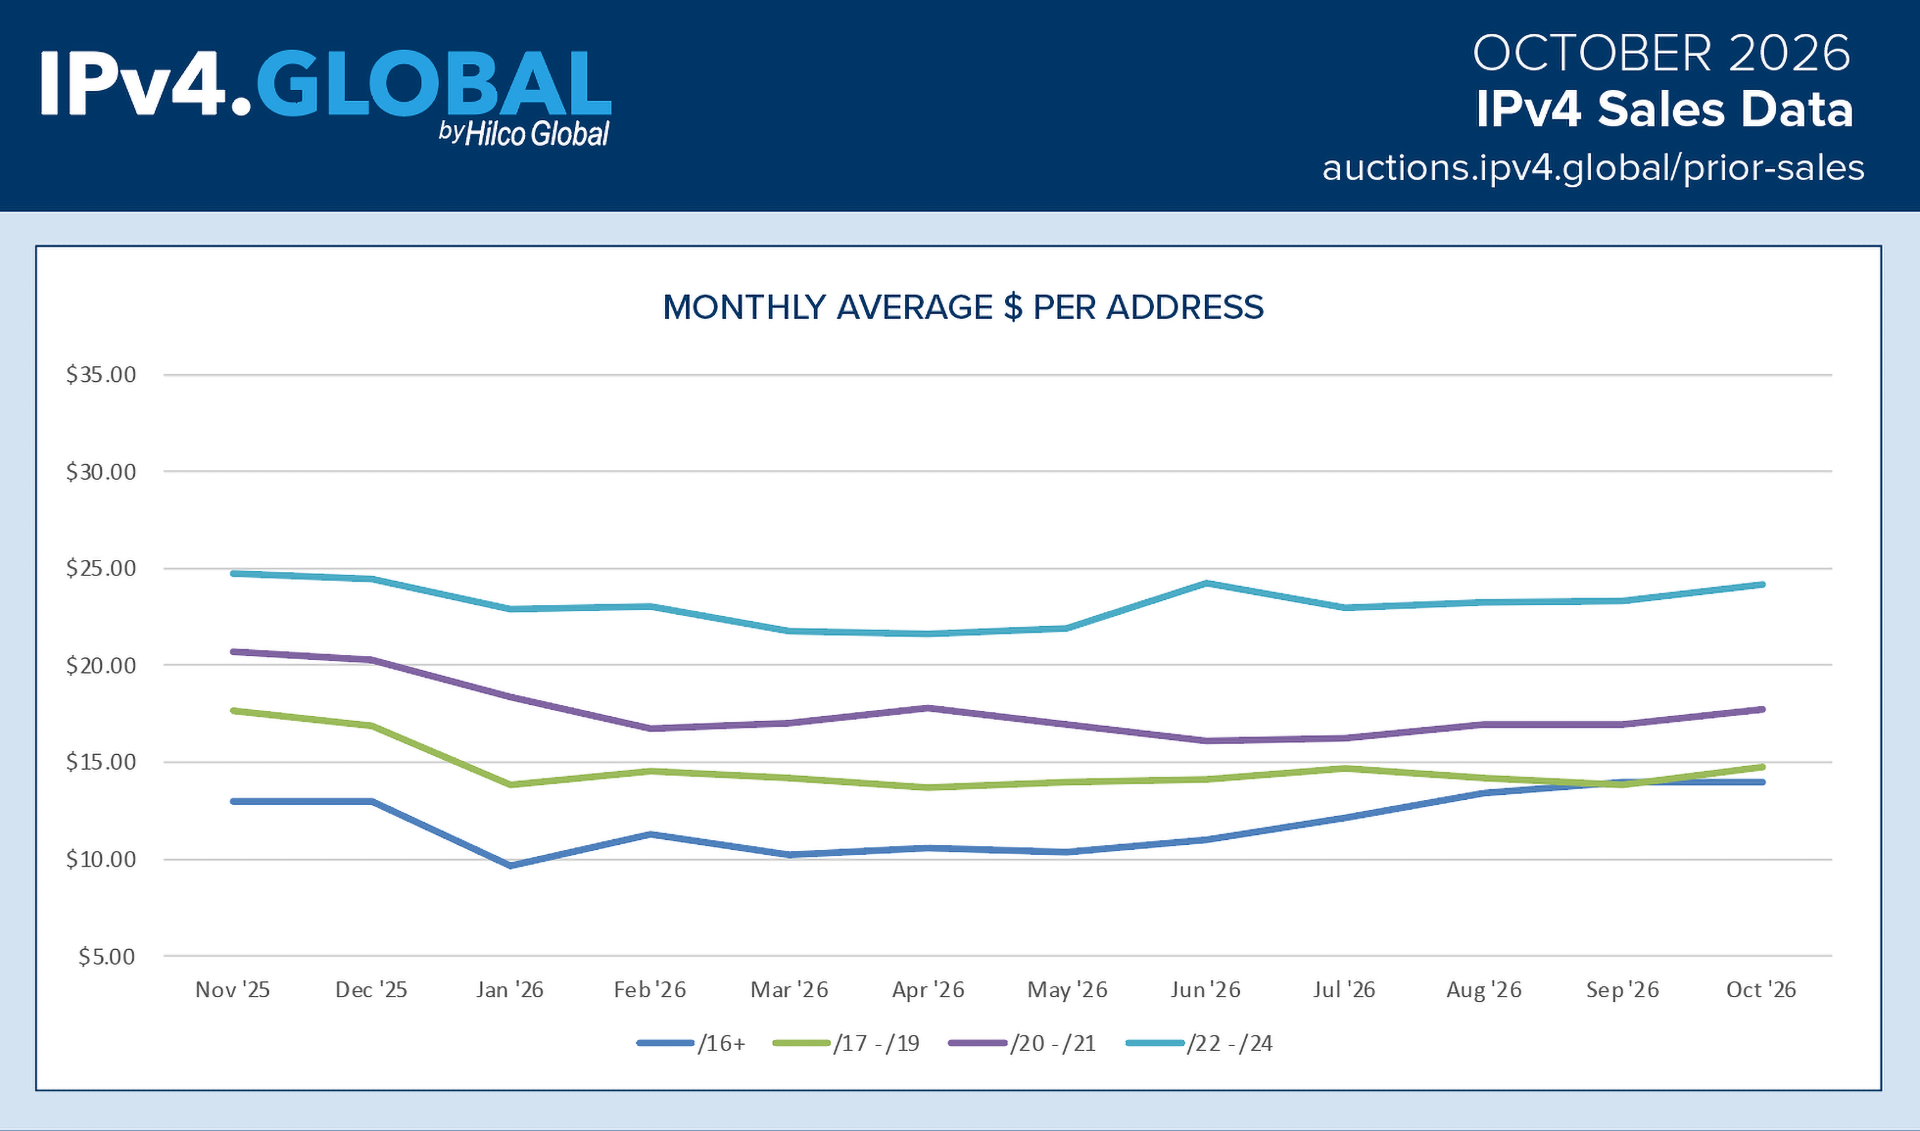
IPv4.Global’s October sales data reveals a notable shift in pricing dynamics. Addresses in /16 and larger allocations averaged approximately $14, compared with less than $10 at their January low. This represents a recovery of more than 40%, making larger blocks the strongest-performing category over that period.
The increase has substantially narrowed the historical discount between large allocations and /17–/19 blocks, which averaged approximately $14.70 in October. This convergence is significant for organizations evaluating the economics of acquiring contiguous address space rather than assembling capacity through smaller purchases.
Other categories also advanced. Average prices for /20–/21 allocations approached $17.70, while /22–/24 blocks reached approximately $24.20 per address, maintaining their substantial premium.
The accompanying chart illustrates the market’s transition from declining valuations in late 2025 to stabilization during spring 2026 and a differentiated recovery thereafter. While October brought increases across all categories, most remain below their November 2025 levels. Larger allocations are the notable exception, having surpassed their earlier average.
October’s price gains occurred alongside steady transaction volumes, suggesting buyers continue to accept firmer valuations. This combination supports the recovery, although it does not independently establish the extent of available inventory or underlying demand.
The broader pattern remains consistent with developments observed since June, when reduced availability of desirable allocations began influencing pricing and buyer competition. Earlier reports highlighted particularly constrained supplies of larger contiguous blocks, where acquisition alternatives can be limited.
Operational requirements across telecommunications, hosting, cloud infrastructure, and enterprise networks continue to support IPv4 demand despite ongoing IPv6 deployment. For many organizations, existing network architectures and compatibility requirements make IPv4 resources a continuing operational necessity.
For buyers, rising prices and narrowing large-block discounts strengthen the case for disciplined acquisition planning. Organizations should evaluate total capacity requirements, deployment considerations, and recent comparable transactions rather than assume historical pricing relationships remain applicable.
For sellers, improved valuations create opportunities to reassess surplus holdings, particularly larger allocations that have experienced substantial appreciation. However, registration history, routing reputation, address quality, and transaction structure remain important determinants of realized prices.
The outlook approaching year-end remains cautiously positive. Sustained transaction activity and constrained supplies of desirable address space could support further incremental appreciation, particularly if larger allocations remain difficult to source.
Nevertheless, October’s broad-based gains do not guarantee continued increases. Additional inventory, changes in buyer requirements, or shifts in transaction composition could moderate pricing.
The market’s progression since spring suggests a transition from post-correction stabilization toward a more established recovery. Whether that momentum continues into 2027 will depend on the balance between available supply, operational demand, and buyers’ willingness to transact at increasingly firm valuations.
Sponsored byCSC
Sponsored byRadix

Sponsored byWhoisXML API

Sponsored byIPv4.Global

Sponsored byDNIB.com

Sponsored byVerisign

Sponsored byVerisign
A World-Renowned Source for Internet Developments. Serving Since 2002.